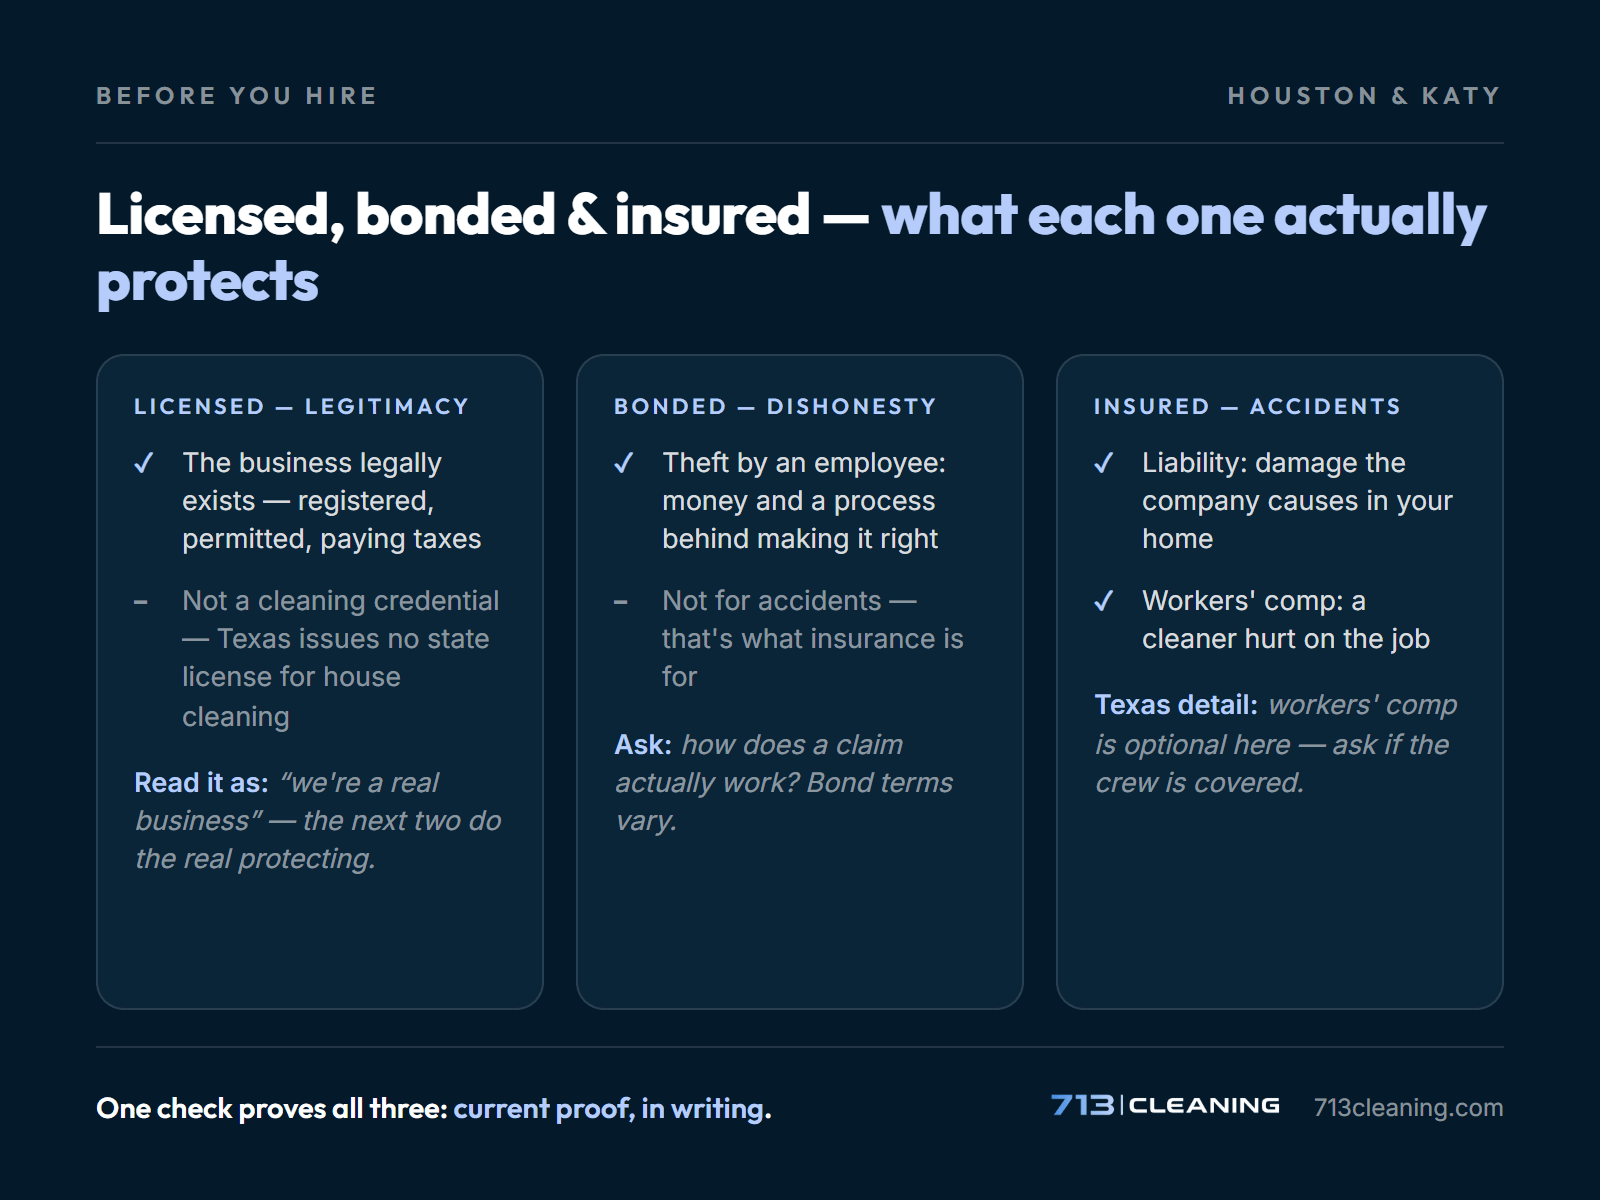
Bonded and insured are two different protections, not one badge: the bond puts money behind making theft right, and insurance covers accidents — from a scratched floor to a cleaner hurt on the job. A company that carries both, and can prove it in writing, has already answered your biggest question.
Comparing companies right now? This is the part that actually protects your home. Here’s what a bonded and insured cleaning service really carries — term by term — plus the one check that proves all three, and the two Texas details most homeowners never hear about.
Key Takeaways
| Term | What it actually protects |
|---|---|
| Licensed | The business is registered and legitimate — but it’s not a state cleaning credential (Texas doesn’t issue one). |
| Bonded | You, from dishonest acts — if something is stolen, there’s money behind making it right. |
| Insured — liability | Your home, from accidents: damage the company causes while cleaning. |
| Insured — workers’ comp | You, if a cleaner is hurt in your home. Optional for Texas employers, so ask. |
| The proof | One check: current proof in writing, sent the same day you ask. |
What a Bonded and Insured Cleaning Service Actually Carries
I run a cleaning company in the Houston area, and “are you bonded and insured?” is the question I most enjoy answering — because the honest answer is a stack of paper, not a yes. The phrase compresses three separate protections into one badge, and they don’t protect the same things.
Licensed: legitimacy, not a cleaning credential
“Licensed” means the business legally exists — registered, permitted, paying its taxes. That matters, but don’t over-weight the word: a cleaning company waving “fully licensed” is telling you it’s a real business, not that anyone certified its cleaning — and in Texas the word carries even less than you’d think (more on that below). The two terms below do the heavy lifting.
Bonded: protection against dishonest acts
A cleaning company gets bonded — usually called a janitorial or fidelity bond — so that theft by an employee has funded recourse behind it. Insurance regulators define fidelity coverage as protection against “loss resulting from an employee’s dishonest act” (NAIC consumer glossary) — in plain terms: if something disappears and an employee is responsible, there’s a pool of money and a process for making it right, instead of a shrug and a denial. Every bond has its own terms, though, so the practical question isn’t “are you bonded?” — it’s “how does a claim actually work?” A good company can walk you through it on the spot.
A client once thought her wedding ring had been taken during a visit. Our documented process — report it, write it down, communicate immediately — kept everyone calm until her husband remembered he’d moved it. That’s what a real process is for: most scares aren’t crimes, and a company that documents everything protects you both ways.
Insured: the accident side — and it’s two policies, not one
General liability is the one people mean by “insured”: it covers accidental damage the company causes in your home. The Insurance Information Institute puts it plainly — liability insurance “pays damages for which the business is found liable… as well as attorneys’ fees and other legal defense expenses” (III small business insurance basics). The scratched floor, the chemical mishap, the broken fixture — this is that policy.
Workers’ compensation is the one nobody asks about: it covers a cleaner injured while working. That sounds like the company’s problem until you remember where the work happens — inside your house. Coverage terms vary by company and situation, so treat this as a question for your own agent too, not legal advice.
The One Proven Check: Ask for Proof in Writing
You don’t have to take anyone’s word for this — one check settles all three protections: ask for current proof in writing before the first visit. For insurance that’s a certificate of insurance — a one-page summary from the insurer showing coverage types, limits, and dates. Ask them to include proof of the bond with it. Any legitimate company can send that the same day.
When it arrives, look at two things: the dates are current, and the name on the certificate matches the company you’re actually hiring. Red flag: “don’t worry, we’re covered” with nothing attached. This is step four of the hiring process — the full guide to finding a housekeeper walks the other six, and the interview around it has its own list of questions.
What It Means in Texas Specifically
Two local details change how you read the badge here:
- Texas doesn’t license house cleaning. The state’s licensing agency regulates more than 50 occupations — electricians, cosmetologists, even auctioneers — and house cleaning isn’t one of them (TDLR’s licensed programs). So in Texas, “licensed” can only ever mean “registered business.”
- Workers’ comp is optional here. In Texas, private employers “can choose to carry workers’ compensation insurance coverage, but it is not required in most cases” (Texas Department of Insurance). Most homeowners assume that coverage is automatic — in Texas it isn’t, so a company can be honestly “insured” for liability while carrying nothing for its own people. It’s worth one extra question: “does that include coverage for your cleaners if they’re hurt on the job?”
Why the Uninsured Quote Is Cheaper
In the homes we quote across Houston and Katy, an independent cleaner typically comes in around 30% below a full-service company — that’s our observation, not market data. And the gap isn’t margin. It’s the cost of the things this article is about: insurance, bonding, payroll obligations, training, backup coverage. A quote without those costs isn’t a discount — it’s a risk transfer. The risk didn’t disappear; it moved to you.
We’ve seen where that lands. A family came to us after — according to the homeowner — a private cleaner ruined a stainless steel appliance with the wrong chemical, then stopped answering and eventually blocked them entirely. That’s one side of one story, and the only side we heard; but it’s precisely the situation a certificate of insurance exists to prevent. If professional pricing is the trade-off you’re weighing, here’s how it typically works — part of every professional quote is buying the paper trail.
What Good Looks Like After You’ve Hired
Six months in, the protections should be boring. The signals they’re real: proof arrived in writing before the first visit without chasing, the company explained its incident process before you asked, and when something small does come up, they raise it first. In ten-plus years bonded and insured, we’ve filed very few claims — smaller things we simply take care of directly, and the rare bigger thing goes through insurance. That ratio is the point: training prevents most problems; the paper is there for the ones it can’t. Once the paperwork checks out, the next expectation to set is the visit itself: what a first professional house cleaning actually includes, and why it runs deeper than the visits after it.
If instead you’re being dodged on paperwork after hiring, that’s the interview failing late — go back to the question list with the next company.
If You’d Rather Skip the Paper Chase
This is the standard we hold ourselves to, so we’re comfortable pointing at it. Our recurring house cleaning is bonded and insured with a background-checked team — run that way since 2015 (more about how we run things here). Ask us for the proof; we like being asked.
Frequently Asked Questions
What’s the difference between bonded and insured? A bond backs you if an employee is dishonest — theft has money behind making it right. Insurance covers accidents: liability for damage to your home, and workers’ comp if a cleaner is hurt. A properly protected company carries both.
How do I verify a company is really insured? Ask for a certificate of insurance before the first visit and read two lines: the dates and the company name. A legitimate company can send it the same day. If getting proof feels like pulling teeth, that’s your answer.
What happens if something breaks and the cleaner isn’t insured? You’re negotiating with an individual, on their goodwill, with no policy behind them — and if they stop answering, there’s usually nowhere to take it. It’s the scenario the certificate question exists to rule out.
Does Texas require cleaning companies to be licensed? No — Texas has no state license for house cleaning as an occupation. “Licensed” from a Texas cleaning company means a registered, legitimate business, which still matters. The protections that do the real work here are the bond and the insurance.